Cisco reports their fiscal Q1 ’27 financial results after the closing bell tonight.
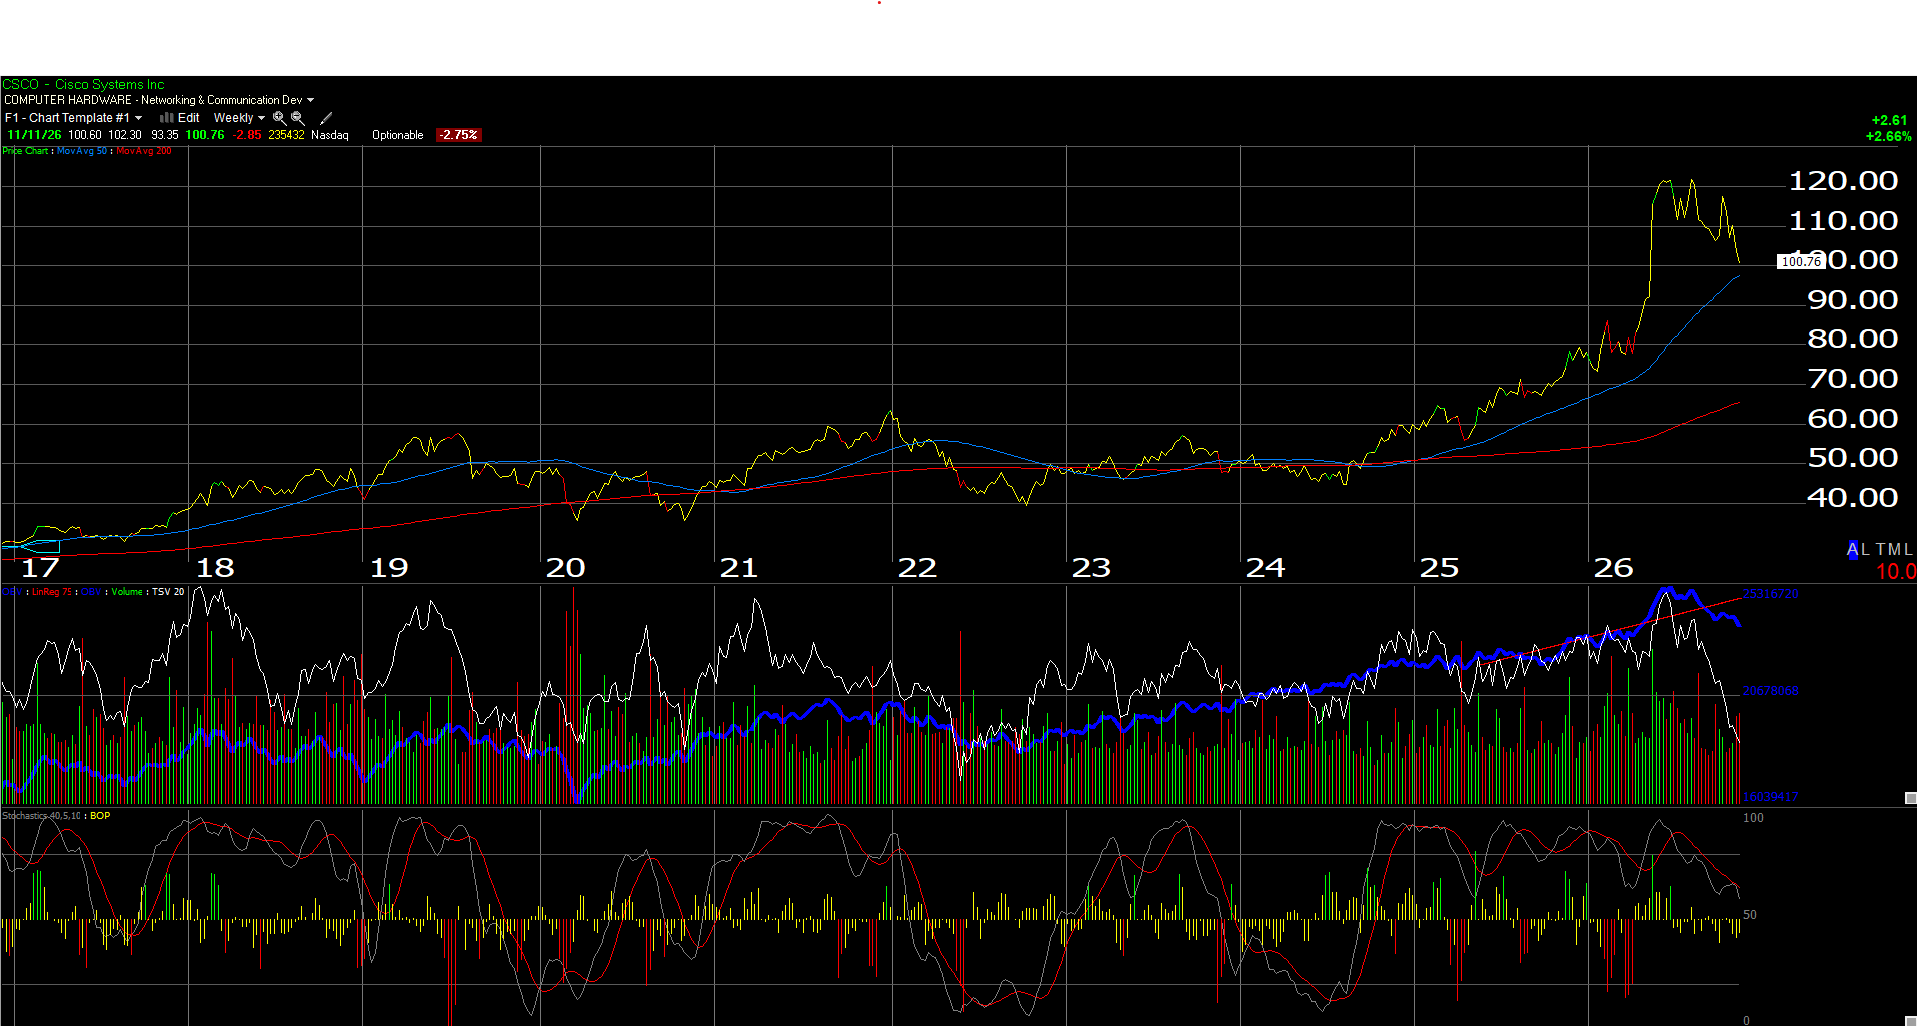
This weekly chart of Cisco shows the networking giant still sitting above it’s 50-week moving average.
The question for readers and investors is, “Will that be the case (stock remaining above the key 50-week moving average) after earnings tonight ?”
Consensus sell-side expectations for Cisco’s Q1 ’27 results are $18.1 billion in revenue, $6.5 billion in operating income and $1.33 in earnings per share for expected year-over-year (y-o-y) growth of 22%, 27% and 33% respectively.
That’s good growth for Cisco: This spreadsheet below shows y-o-y growth for all the PL components, dating back 12 quarters:
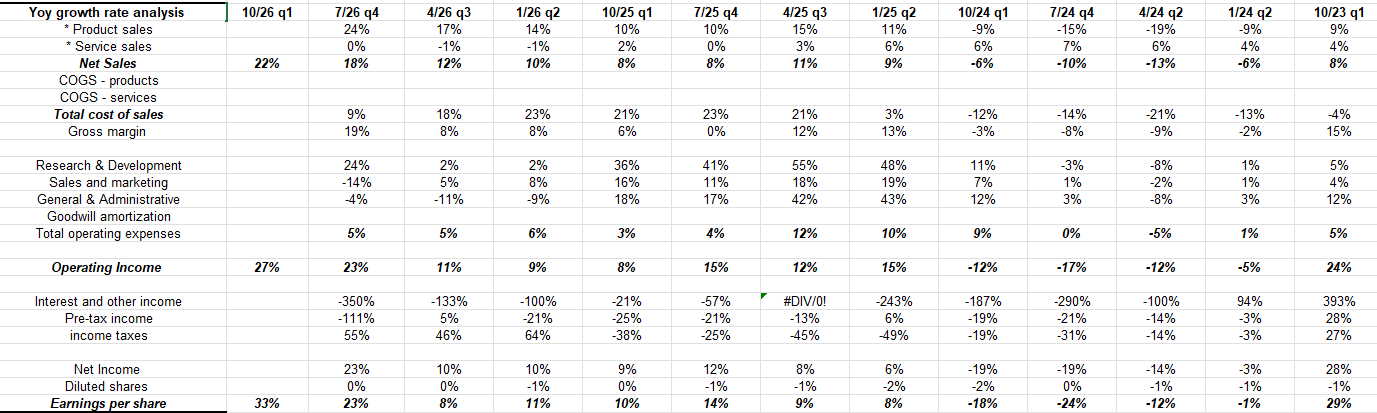
Fiscal Q4 26’s revenue growth of 18% was the best quarterly revenue growth for Cisco since July ’23.
Fiscal 26’s full-year revenue growth of 12% was the strongest annual revenue growth rate since the 11% growth rate in 2010, so yes 26’s full-year revenue growth was the strongest in 16 years.
For full-year fiscal ’27, Cisco is expecting $5.13 in EPS, $72 billion in revenue and operating income of $25.5 billion for expected full-year fiscal ’27 growth of 19%, 15% and 16% growth respectively.
A quick note on valuation:
Cisco is expecting to earn $5.13 in EPS in fiscal ’27 and then $5.58 and $6.11 in in fiscal ’28 and fiscal ’29, and with the stock trading at $100 per share with last night’s close, CSCO is trading at 19x, 18x and 16x those estimates.
Expected revenue growth in fiscal ’27 is $72.9 billion, $78.1 billion and $83 billion for expected revenue growth the next 3 years of 15%, 7% and 6%.
Cisco’s cash-flow valuation is not cheap at all at 30x and 36x cash-flow and free-cash-flow respectively.
Summary: With recent events around Nvidia, including today’s resignation of Jensen Huang as Nvidia CEO, not to mention the rather poor action in AI hardware stocks since June 30th ’26, I’m more cautious around Cisco since it’s been a tech laggard in general, with the exception of calendar 2026 with the stock up 33% as of last night’s close. (No positions owned in NVDA directly, but do own NVDA for clients through the Nasdaq 100 ETF (QQQ).
Cisco’s all-time-high in the late 1990’s was $82 per share in April of 2000, when it went through a 10-year period where annual revenue growth was 50% – 100% per year.
Cisco only took out it’s April, 2000, all-time-high in February ’26.
Cisco’s networking business is still 57% of total revenue, which has grown at 20%-plus the last three quarters, with product revenue growing +24% last quarter. Per management on the conference call, AI revenue in fiscal ’26 was $4 billion (just over 4% of Cisco’s total revenue in fiscal ’26 of $63 billion), with $9.5 billion in orders exiting fiscal Q4 ’26.
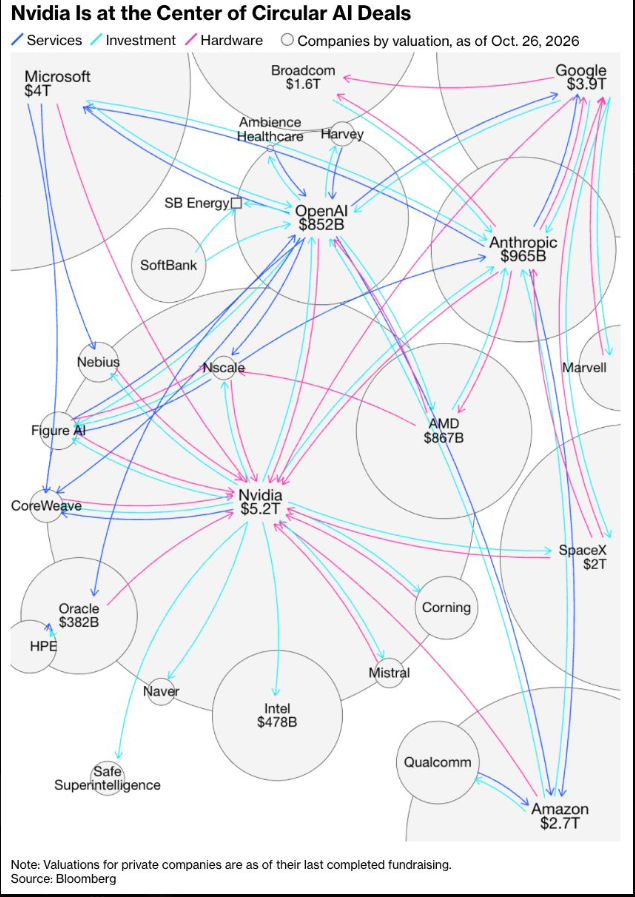
The Nvidia issue with the circular financings as detailed here by a diagram posted to X by Ayesha Tariq, CFA. Th issue is not that Cisco is heavily exposed to this – Cisco does not appear on the diagram at all – but Jensen’s departure could have a trickle-down effect on the entire sector as this whole thing plays out. In addition, the mid-term election results were not encouraging for the data center build-out program.
Cisco is nowhere close to being the momentum stock it was in the 1990’s but it did trade up to $130 per share over the summer.
This blog holds a 1% position for clients and will wait and see how the fiscal Q1 ’27 results look, and what guidance looks like relative to expectations for fiscal ’27 (ends July ’27).
None of this is advice or a recommendation but only an opinion. Past performance is no guarantee of future results. All EPS and revenue estimate data is sourced from LSEG. None of this information may be updated, and if updated, may not be done in a timely fashion. Positions may change at anytime as well.
Thanks for reading.