First, a little housekeeping around SP 500 expected EPS growth numbers:
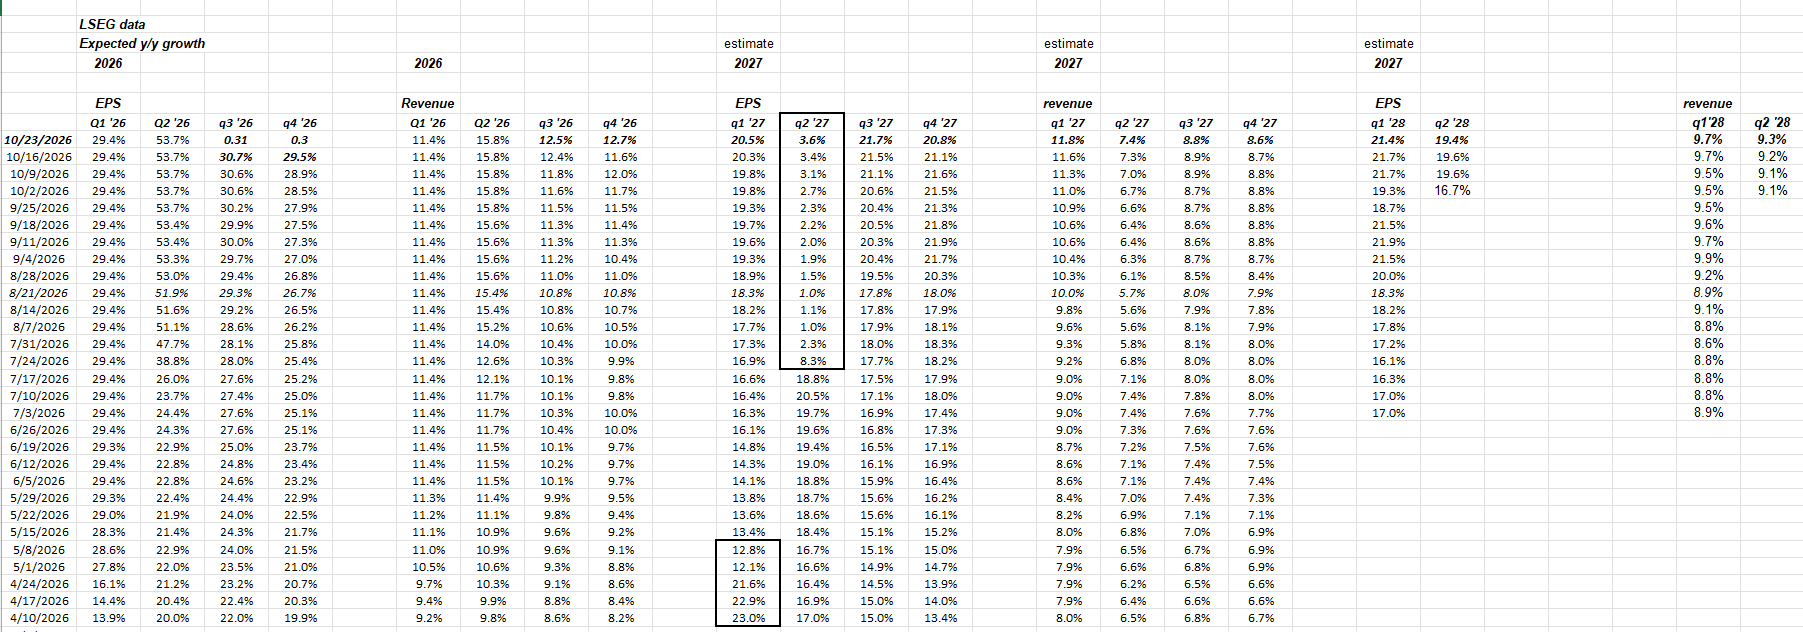
Here’s the trend in expected y-o-y EPS and revenue growth rates for the SP 500 for Q3 ’26 through early 2028.
Q1 and Q2 ’26 columns are already over and done with, but they were left displayed on the s/sheet for comparison purposes for readers.
The two dark-bordered areas show the estimated growth rates in EPS for 2027 after the Q1 ’26 Anthropic non-operating mark-ups at Alphabet and Amazon, and then the Q2 ’26 mark-ups, again for both Alphabet and Amazon, both impacting Q1 and Q2 ’27 from a comparison standpoint.
For Q1 ’26, note how the Q1 ’27 revision lower in SP 500 EPS, was almost immediately overridden by upward revisions on the table. Readers can see the drop from an expected low-20% EPS growth rate to 12.1% and then by July 31, the expected EPS growth rate was back to 17.1% and has kept climbing.
Now look at Q2 ’27: the current Q2 ’27 expected EPS growth rate for the SP 500 is just +3.6% as of this weekend, which would be the lowest quarterly growth rate for SP 500 EPS since Q2 ’23’s -2.8%. It has not seen the same level of revision.
It’s still 9 months out from Q2 ’27’s earnings releases, which won’t start until mid-July ’27.
Trying to analyze data like this will drive you nuts, but note the change in estimated EPS growth between Q1 and Q2 ’27. Analysts were much more confident (and still are) in Q1 ’27 EPS growth expectations, while there is suddenly cold feet with Q2 ’27’s EPS growth.
But Q3 and Q4 ’27 still look strong and healthy per the above numbers.
Q2 ’27 may be a tough overall “earnings compare” given what semiconductor stocks and SP 500 EPS / revenue did in Q2 ’26.
If readers are wondering what the “average” quarterly growth rate is for SP 500 EPS: from Q4 ’11 through Q4 ’19, the “average” quarterly SP 500 EPS growth rate per quarter is 7.3%. Excluding the COVID period from Q1 ’20 through Q4 ’21, the average quarterly SP 500 EPS growth rate per quarter from Q1 ’22 through Q2 ’26, is 19.8%. (Thanks, AI.)
FOMC meeting Wednesday, October 28th:
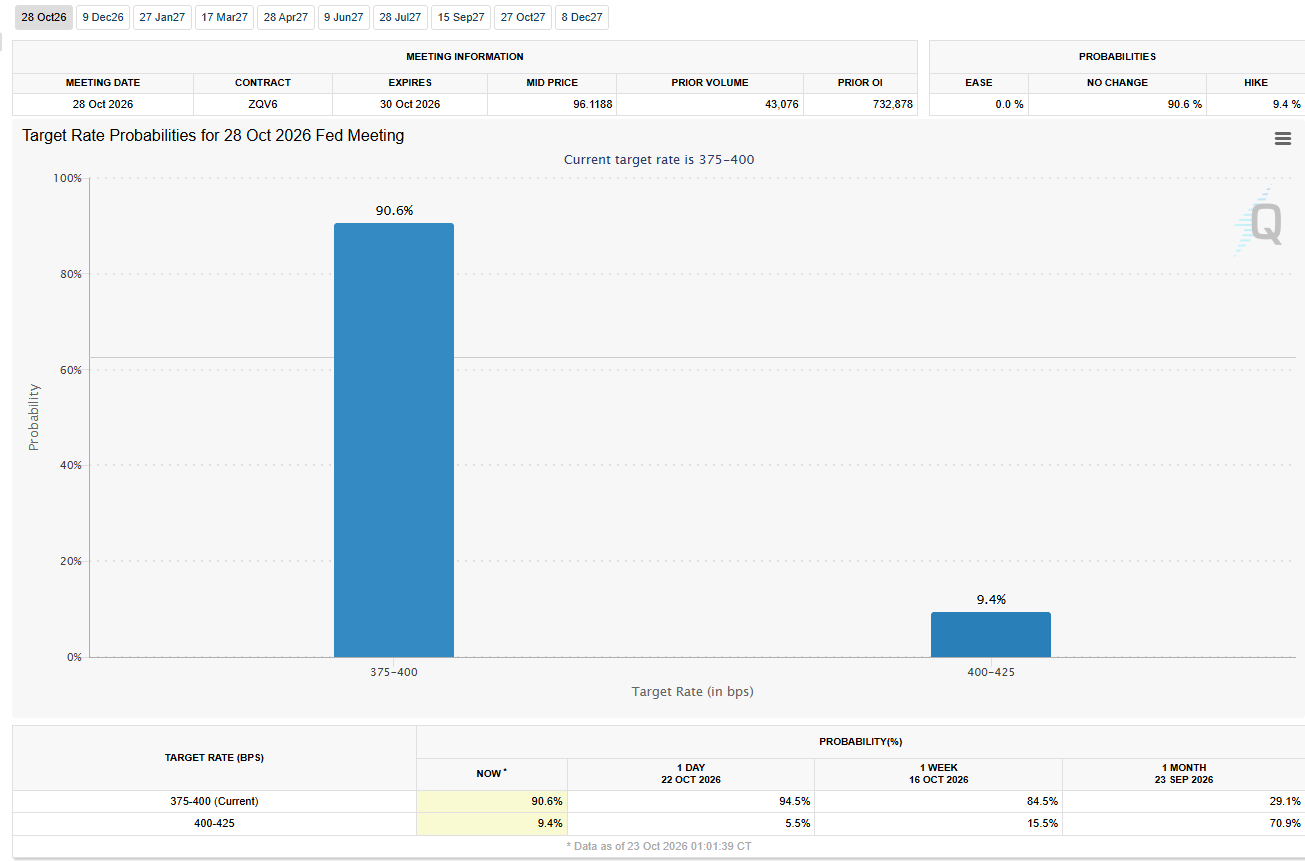
There is very little chance of a fed funds rate hike Wednesday, October 28th. David Kelly, JPMorgan’s Chief Global Strategist noted that it would be highly unlikely to change monetary policy that close to a mid-term national election.
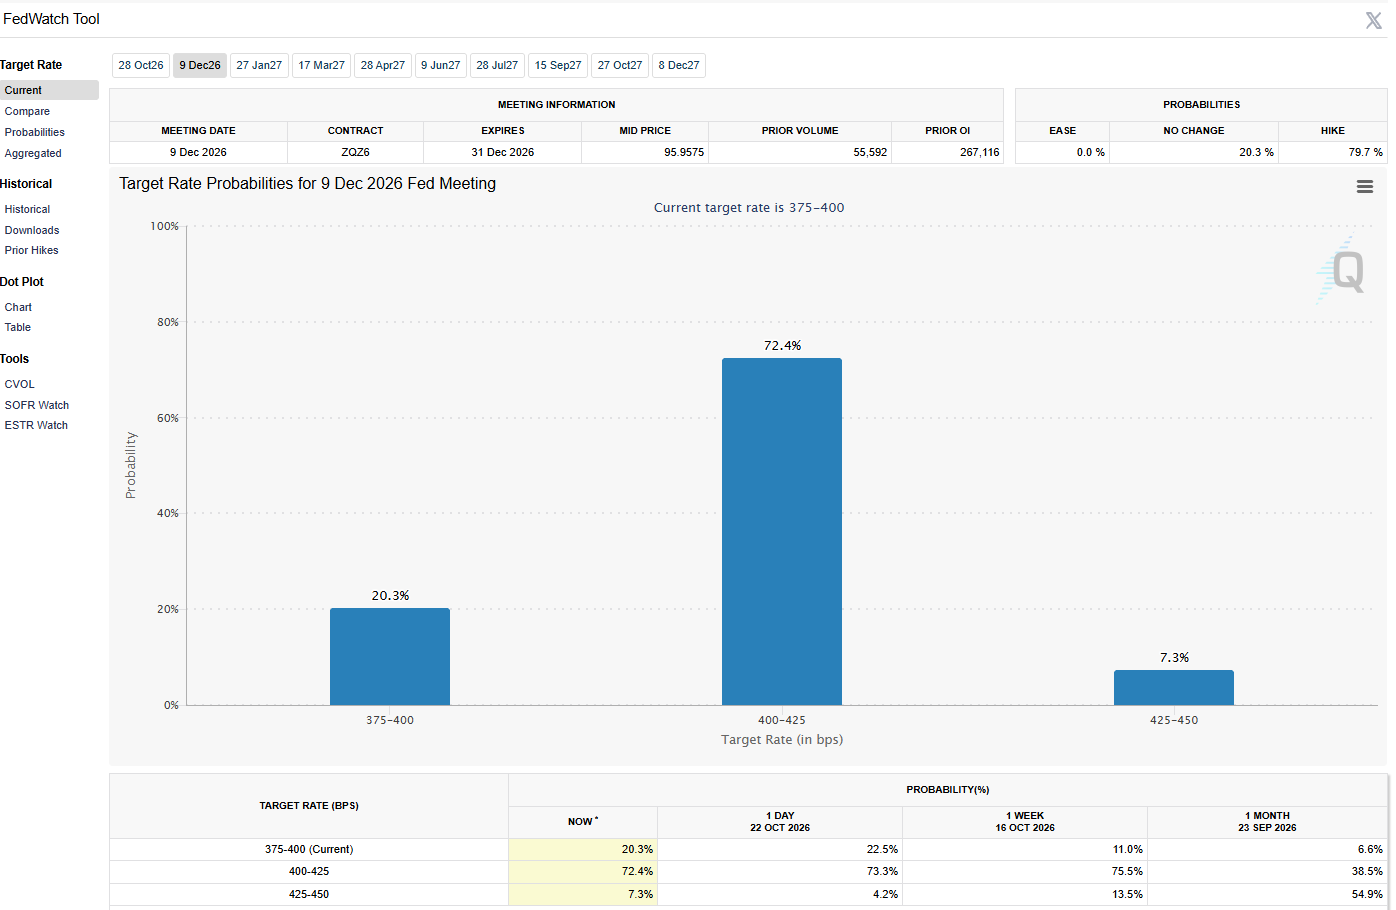
However, the December 9th FOMC meeting is almost certainly look for a 25 bp bump to a midpoint of 5%.
September PCE and Core PCE next week:
Thursday morning, 10/29/26 we will get the first look at Q3 ’26 GDP which is expected at +3%.
More importantly than GDP will be the September PCE and Core PCE, given inflation worries. Overall September PCE is expected at 0.4%, while Core PCE, which is the more important metric of the two, is expected at +0.3%.
Hyperscaler earnings:
Alphabet and Microsoft will report earnings after the bell on Wednesday, October 28th, while Amazon will follow on Thursday, October 29th, after the closing bell. Earnings previews will be forthcoming this weekend.
Summary: Wednesday, October 28th this coming week will be quite busy with PCE being released at 7:30 am (central time), the FOMC announcement being released at 1 pm (central time) and then possibly the biggest news given the market action the last few weeks, Alphabet (GOOGL) and Microsoft are releasing their September ’26 quarterly earnings after the bell. (For Microsoft, this will be their fiscal Q1 ’27 earnings release).
Since it’s likely we already know the outcome of the FOMC meeting given fed funds futures, the PCE data could be the market-moving event for bonds, while the earnings reports will surely impact the stock market Thursday and Friday.
The persistent bid in WTI crude oil is not good, which now above $103. As long as WTI crude doesn’t make a new all-time-high, which was $113 and change in early April ’26, it’s still (relatively) contained.
None of this is advice or a recommendation, but only an opinion. Past performance is no guarantee of future results. All of the SP 500 EPS and revenue data is sourced from LSEG. None of the information above may be updated, and if updated may not be done in a timely fashion.
Thanks for reading.